Are we approaching an MA profitability cliff?
For the better part of a decade now, the general industry view on Medicare Advantage has been one of overwhelming positivity. It’s been a steadily growing profit center for legacy plans and providers, and a relatively safe bet for newer market entrants and healthcare investors.
At a glance
Read on to get our full commentary, or use the links below to jump to a specific area of interest:

For the better part of a decade now, the general industry view on Medicare Advantage has been one of overwhelming positivity. It’s been a steadily growing profit center for legacy plans and providers, and a relatively safe bet for newer market entrants and healthcare investors. The “why” behind this sentiment is relatively straightforward: enrollment growth in MA has only continued to accelerate—as of just this year, more seniors are enrolled in MA than in traditional Medicare—and its profitability (to plans, at least) is more than double that of any other business line.
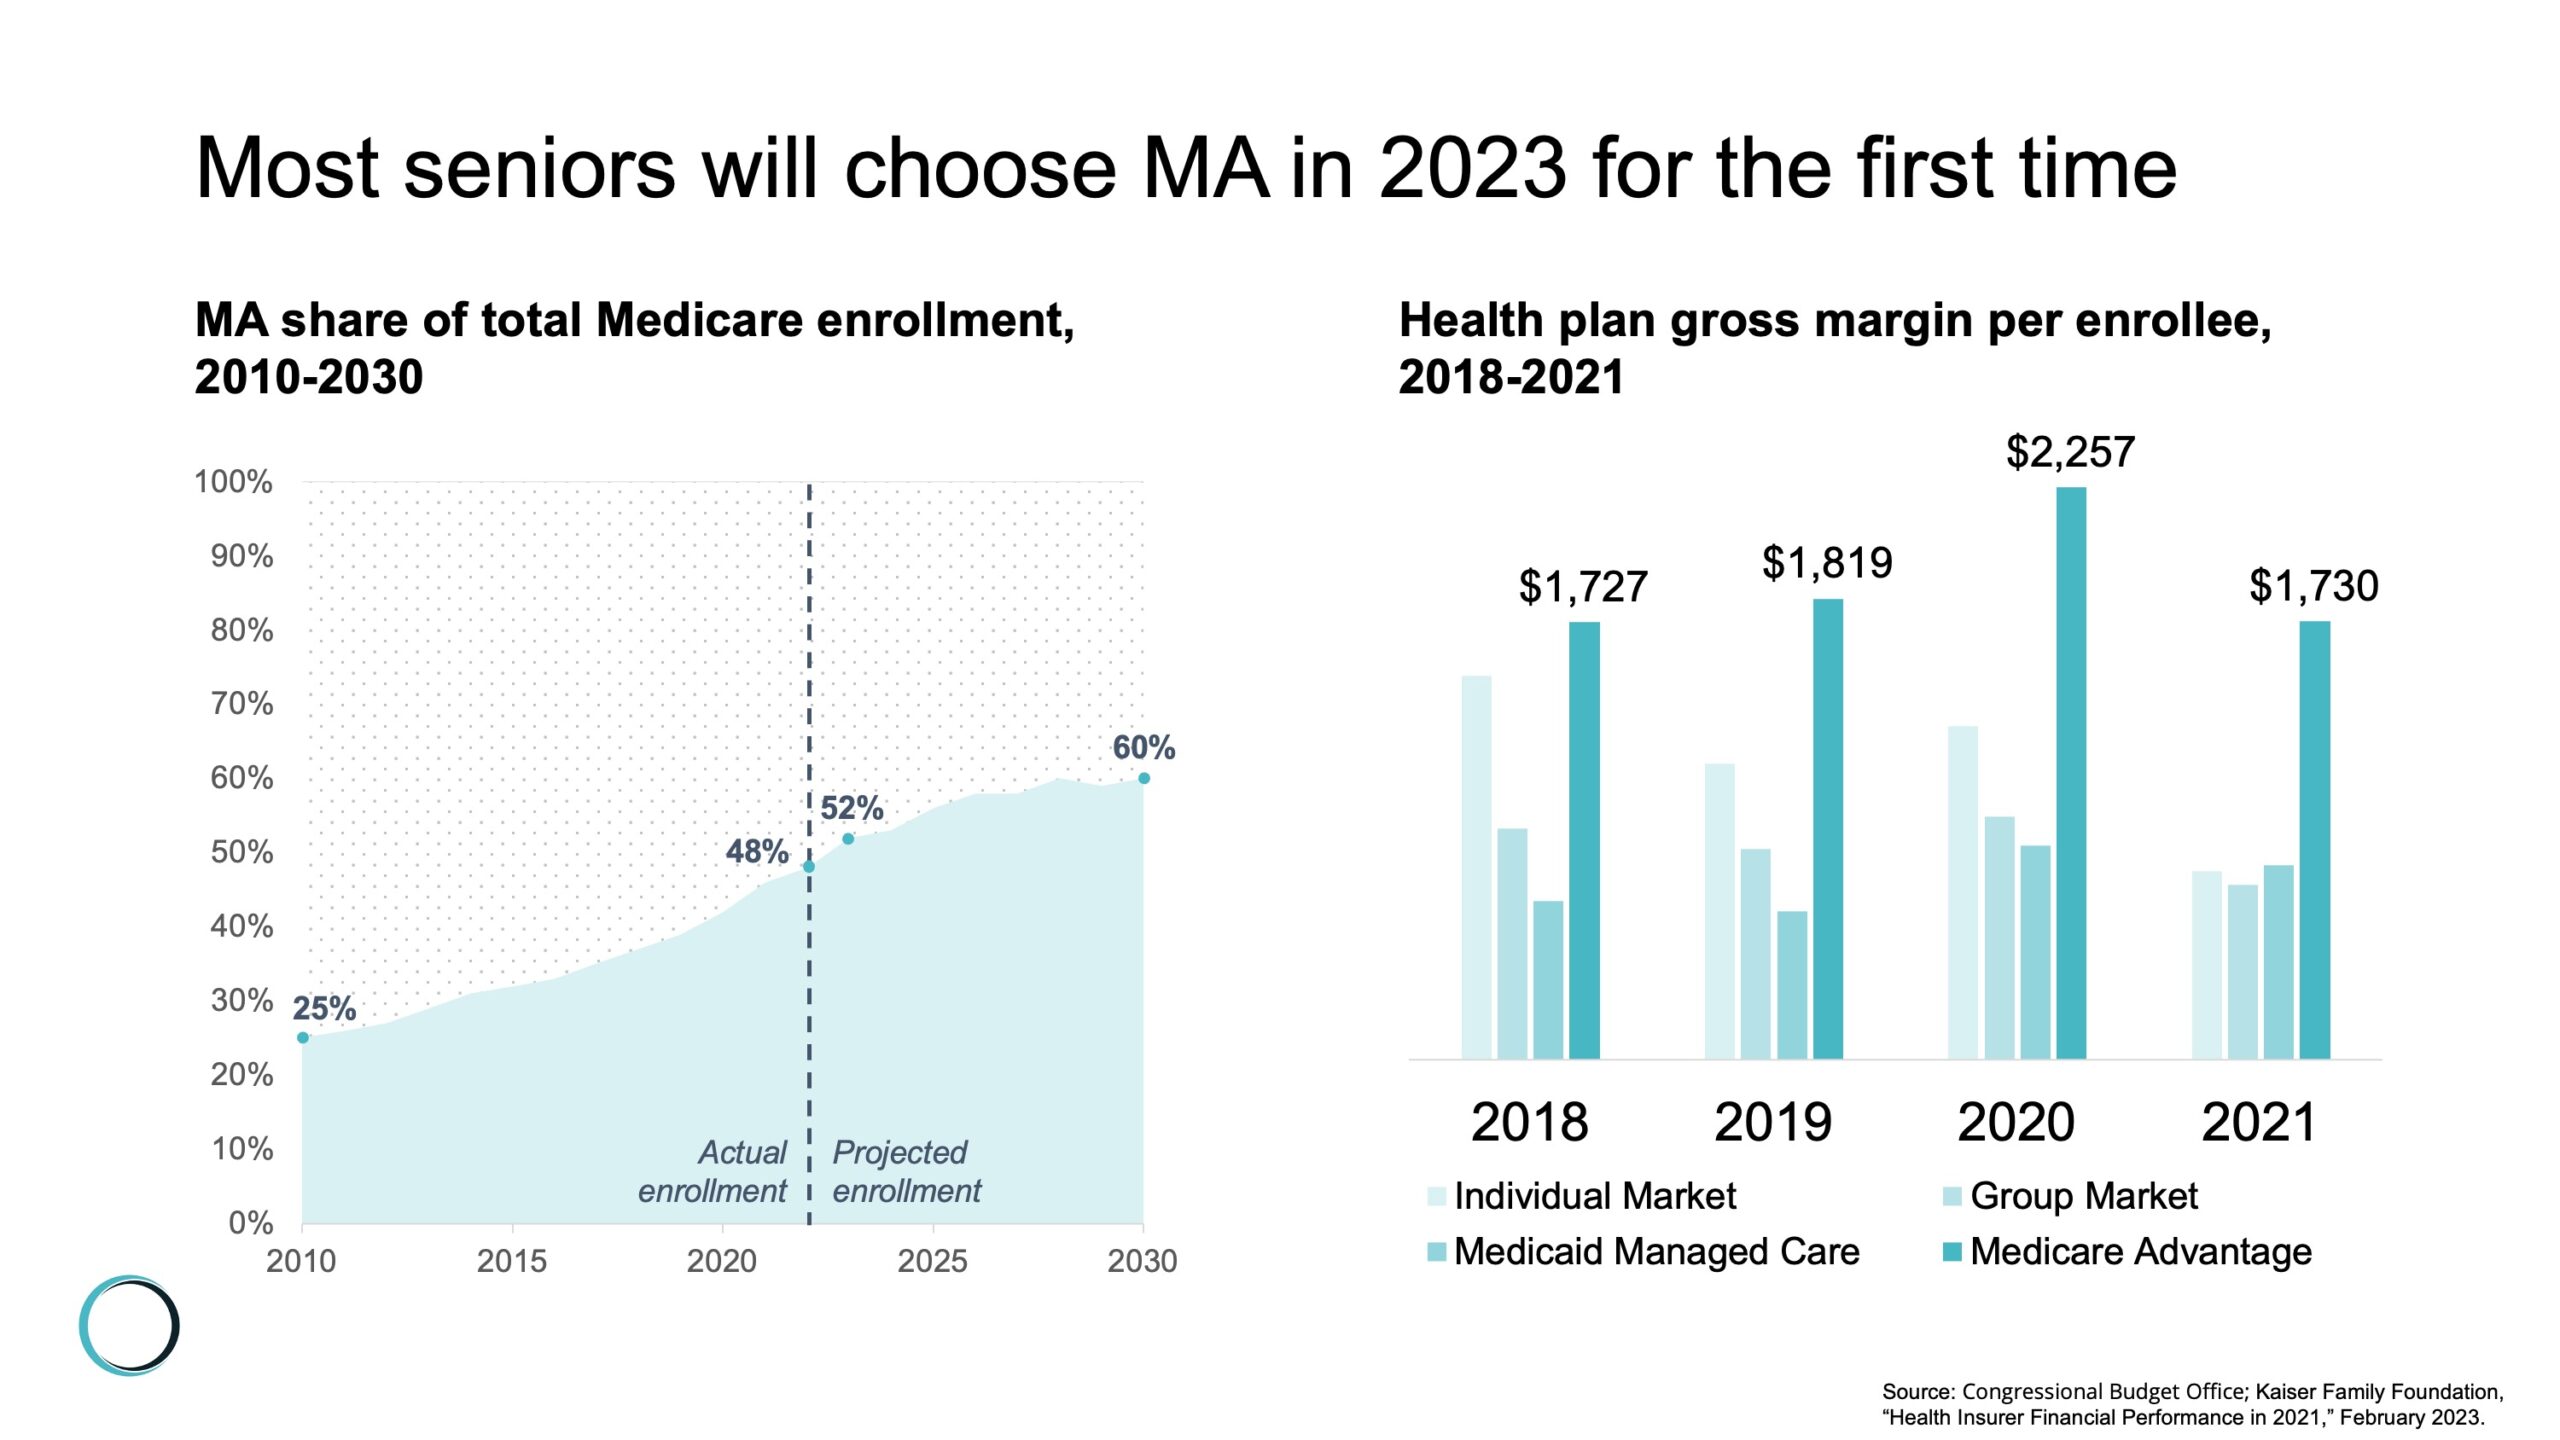
But more recently, I’ve begun to hear rumblings of a different story on MA crop up with greater frequency. As MA has grown, it has also attracted more scrutiny and more competition, and some of the savviest healthcare strategists I know have begun to question whether we might be approaching an MA profitability cliff—whether driven by a policy-enabled crackdown on MA reimbursement and spending, or by the over-saturation of the market with new competitors, or a combination of both.

Union Healthcare Insight
Log in to continue reading
Not a member yet? Create a free account for limited access.

Let’s talk.
Questions? Want to learn more about what Union can do for you? We’d love to hear from you.
Related insights
This week in healthcare: What happened and what it means
What the 2026 midterm election results mean for healthcare policy
Healthcare policy and payment: What leaders need to know now